The Market Common
About The Market Common
Walkable urban-village living with shops, dining, and parks in the heart of Myrtle Beach.
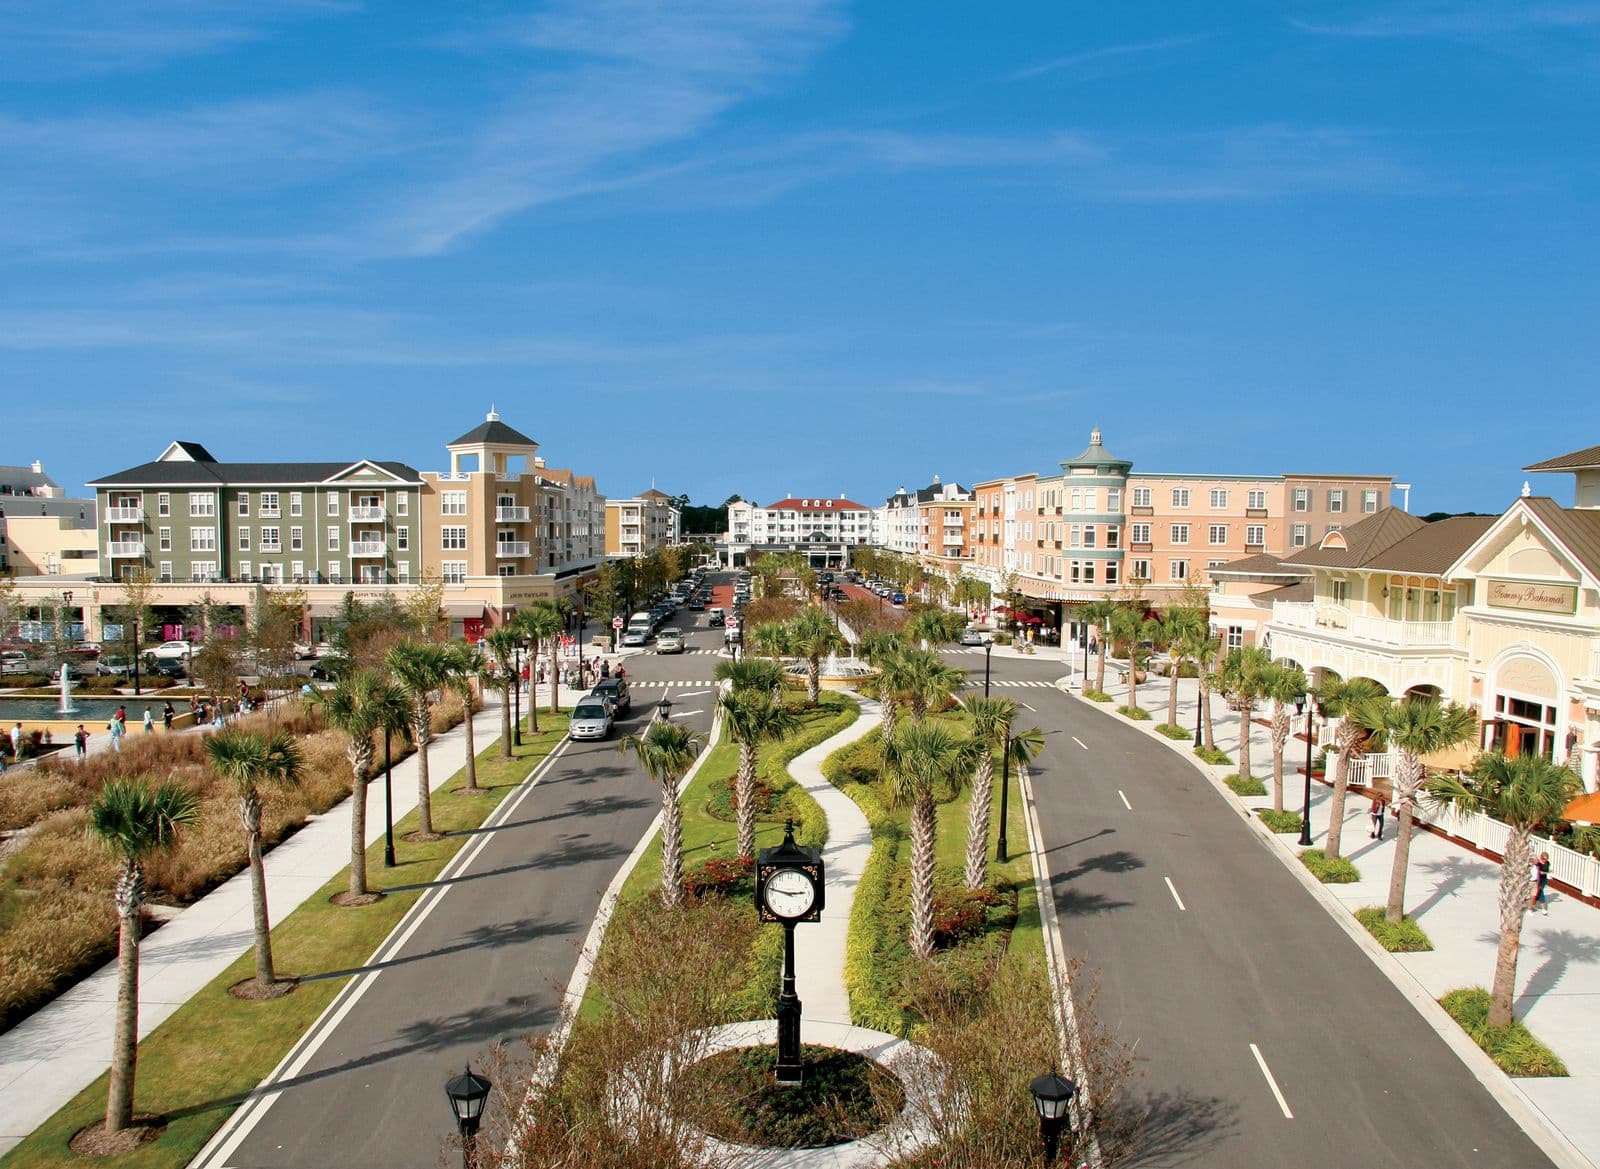
Built on the former Myrtle Beach Air Force Base (closed March 1993), The Market Common is now a walkable, mixed-use neighborhood of shops, restaurants, parks, and homes — the closest thing the Grand Strand has to true walkability. A strong fit for anyone who wants an urban-village feel over a typical suburban or beach-town layout.
Life in The Market Common
Walkability
True walkability — shops, restaurants, and parks within walking distance of most homes
Parks & Green Space
Parks and green space throughout, including Warbird Park and the Grand Park Athletic Complex
Urban-Village Feel
Distinct from the rest of the Grand Strand's suburban or beach-town layouts
What The Market Common offers
- Low-maintenance living
- Shops, restaurants and parks on foot
- An urban-village street grid, not a subdivision
Around The Market Common
The Market Common sits inside the city of Myrtle Beach rather than beside it, a few minutes back from the oceanfront. Surfside Beach is the next town south for anyone who wants the sand closer than the shops, and Grande Dunes is the comparison most buyers end up making — amenities built into a gated community, against a walkable street grid you can leave on foot.
For how it reads next to the rest of the coast, start with Best Places to Live on the Grand Strand. If you're arriving from out of state, the relocation guide covers South Carolina residency, timing a move around hurricane season, and utilities. When you want to see everything currently listed here, use the Market Common property search.
Search homes for sale in The Market Common
Loading live MLS listings…
Questions about The Market Common
Short answers, with the full explanation one click away. General information, not legal, tax or insurance advice — South Carolina requires a licensed attorney to conduct your closing.
Is a home in The Market Common inside South Carolina's coastal area for wind insurance?
The test is statutory: § 38-75-310(5) draws Horry County's coastal area as everything east of US 17 or Bypass 17, whichever runs farther west. The Market Common sits between the Bypass and the ocean, which puts it inside — and inside that line, wind and hail can legally be excluded from a homeowners policy and bought separately, with a second deductible. A specific address can sit on the far side of that road from the rest of its street, so the declarations page and your insurance agent settle it — not the town name. How wind and hail coverage works here →
Will I need flood insurance on a home in The Market Common?
That is a per-parcel question, not a per-town one — zones change block to block and sometimes lot to lot. What decides it is the FEMA flood zone for the specific parcel: inside a Special Flood Hazard Area (the A and V zones) federal law directs a regulated lender not to make, increase, extend or renew the loan unless the building is covered for the term of it. Zone X carries no federal mandate, though a lender may still require coverage as a matter of its own policy. Pull the zone for the actual address before you write an offer, never a neighborhood-level impression. Flood zones, decoded →
How is property tax figured on a home in The Market Common?
South Carolina assesses an owner-occupied legal residence at 4% and everything else — second homes, rentals, land — at 6%, under S.C. Code § 12-43-220. Those ratios are state law, so they apply the same in Horry and Georgetown counties. The 4% is not automatic: you have to apply for it, and the Horry County Assessor's guidance is blunt about the consequence of not doing so — an automatic 6% assessment. The rest of the bill depends on the taxing districts the parcel sits in, so ask the county assessor for the real figure on the real address before you rely on any of it. Horry County property taxes, explained →
What should I check on the HOA before buying in The Market Common?
The recorded set is the real set. Under South Carolina's Homeowners Association Act, a community's governing documents must be recorded to be enforceable, and its rules and amendments must be re-recorded by January tenth of each year following adoption to stay enforceable. Pull the recorded documents from the county Register of Deeds and compare them against the packet you were handed. If a rule that would change your purchase — a rental restriction, a vehicle rule, an architectural standard — is in the packet but not in the county record, that is a question for your closing attorney before you close. Buying in an HOA here →
Thinking about The Market Common?
Robin lives and works the Grand Strand every week — ask her what the listings don't tell you.